Aluminum Scrap Markets
October 20, 2026
AMU Survey: Aluminum scrap outlook splits on prices
Written by Nicholas Bell
The aluminum scrap outlook shifted sharply in October as recycler forward views moved toward undersupply while Midwest Premium and UBC expectations moved lower. Half of recyclers expected an undersupplied market three months ahead, but 60% expected a lower Midwest Premium and none expected higher UBC prices.
Current recycler demand remained mostly stable, while inventory drawdowns changed little.
Scrap supply expectations shift toward undersupply
The aluminum scrap outlook underwent its largest month-to-month shift in the three-month supply balance question.
Half of recyclers expected an undersupplied market three months ahead. One-third expected oversupply, while about 17% expected balance.
September was almost the reverse. About 75% expected oversupply and 25% expected undersupply, with no balance responses.
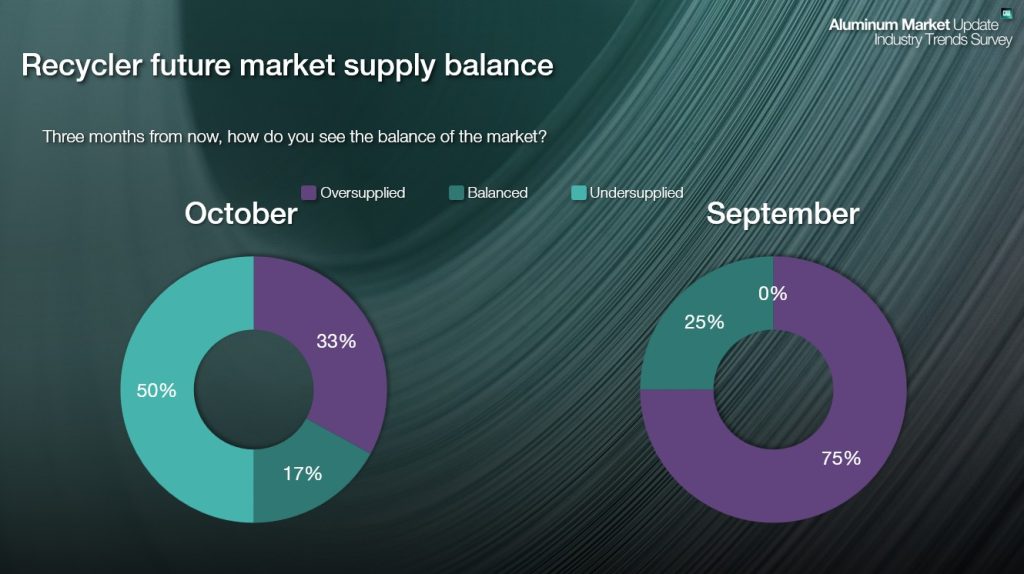
October moves recycler expectations toward undersupply without creating a consensus.
Midwest Premium expectations turn lower
The shift in the aluminum scrap outlook did not translate into expectations for a higher Midwest Premium.
About 60% expected a lower Midwest Premium next month, while 40% expected stability. No recycler expected an increase. September had been 75% stable and 25% higher, with no lower responses.
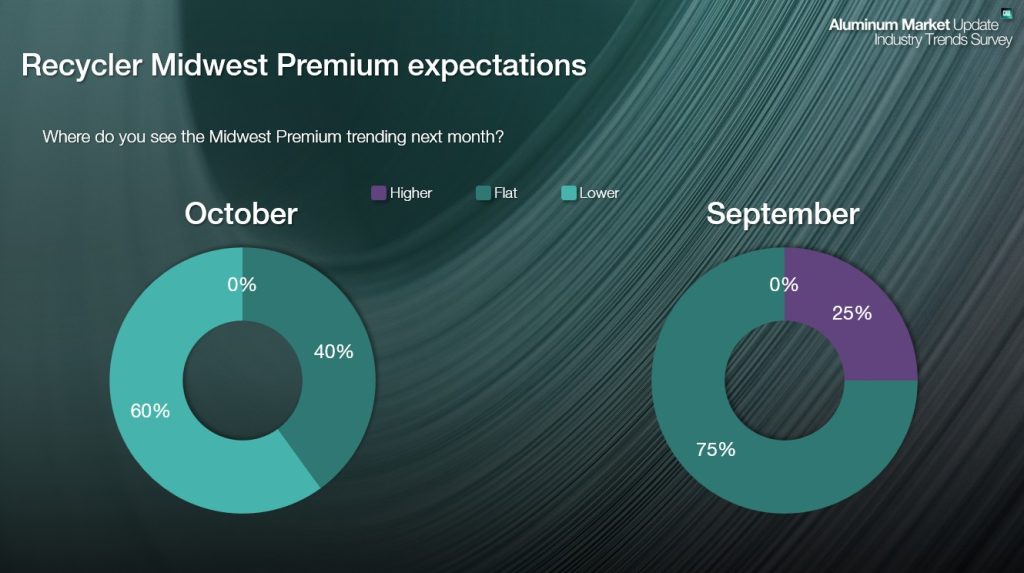
Recyclers leaned more heavily toward lower expectations than the rest of the market. About 36% of nonrecyclers expected a lower premium in October.
UBC expectations lose the higher category
UBC expectations moved less sharply but also shifted away from higher prices.
About 83% of recyclers expected stable UBC prices next month. The remaining 17% expected lower prices, while none expected an increase.
September had been 75% stable and 25% higher.
Across all respondents, about two-thirds expected stable UBC prices and one-third expected lower prices. No respondent selected higher.
The UBC and forward-balance questions measure different parts of the market.
Outright UBC prices can move with the underlying aluminum benchmarks as well as the percentage buying level. A tighter expected scrap balance does not require higher outright UBC prices.
Recycler outlook for exports shifts higher
Meanwhile, recycler export demand shifted toward increasing or stable conditions after September’s more declining responses.
About 25% reported increasing export demand in October, while 75% reported stability. No recycler reported declining export demand.
September had no increasing responses. About 29% reported declining export demand, while the remainder reported stability.
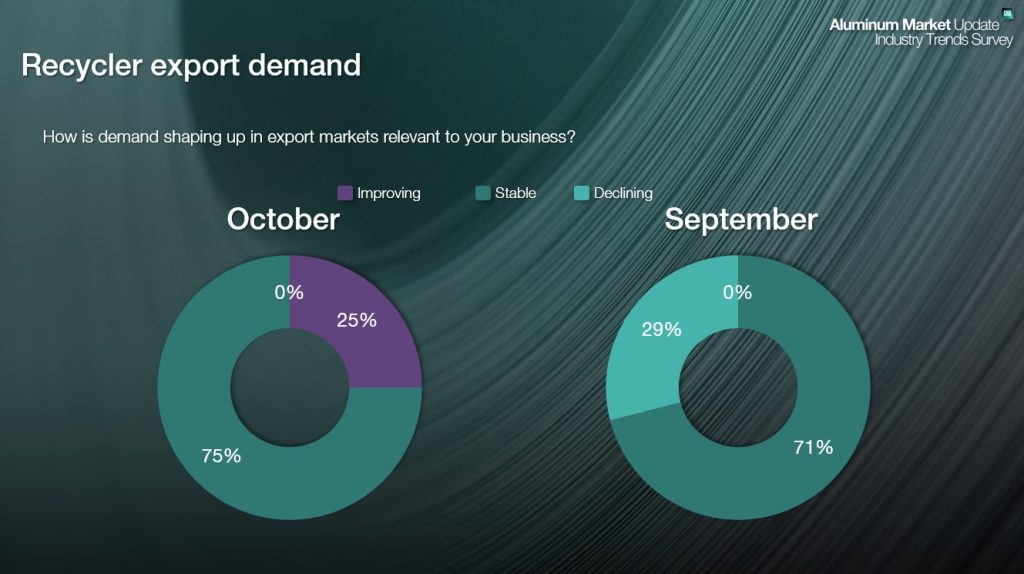
October resembles August more closely, when 40% reported increasing export demand and 60% reported stability.
The change could fit with recyclers becoming less comfortable with the forward domestic balance.
Current recycler demand centers on stability
Current recycler demand became much less divided in October.
About 83% reported stable demand, while 17% reported improvement. No recycler reported declining demand.
October did not see an increase in the share of improving responses. Instead, a greater share of responses centered on stable.
September was split between 50% stable, 25% improving and 25% declining.
Recycler demand weakened in July, shifted in August and became divided again in September. October brings the distribution back toward stability.
Inventory drawdowns remain limited
Recycler inventory management changed little from September.
About 80% kept inventories steady in October, while 20% reported drawing down. September was 75% steady and 25% drawing down.
The larger adjustment occurred earlier. About 70% of recyclers reported drawdowns in July, followed by 67% in August.
October extends the inventory pattern established in September rather than starting another directional move.
Future scrap supply expectations contrast with current availability
About 80% of recyclers said enough obsolete scrap was available to meet demand. The remaining 20% reported insufficient supply.
September was split 75% yes and 25% no. July also came in at 80% sufficient, while June was 71%. August was the recent low at 60%.
Tangentially, every nonrecycler answering the October question reported sufficient obsolete scrap.
Lead times show limited current pressure
Recycler qualitative lead times moved slightly outward.
About 80% reported stable lead times, while 20% reported extension. Every recycler reported stable lead times in September.
The change moves in the same direction as the forward balance, but most recyclers still reported stable lead times. The current readings provide limited support for calling the scrap market immediately undersupplied.
Putting it together
October’s recycler results showed a widening separation between forward supply expectations and price forecasts.
Demand remained predominately stable, inventory drawdowns were limited and obsolete scrap availability stayed within its recent range.
Recyclers anticipated a tighter physical balance ahead while expecting lower or stable prices over the shorter term.