AMU's monthly survey is out. Let us know what you think.
Don't just read our survey results. Help shape the conversation by participating with firsthand insights.
Don't just read our survey results. Help shape the conversation by participating with firsthand insights.
Construction spending indicators show softer architecture billings and private construction spending despite strength in several large project categories.
US construction indicators show large projects supporting planning and starts even as contractor backlog and broader commercial activity lose momentum.
Extended Producer Responsibility laws could advantage aluminum.
And, of course, AMU Summit coverage, which included topics ranging from prices, primary, data centers, autos and more.
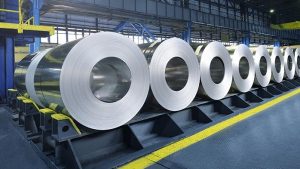
Kloeckner says aluminum service centers are taking on more processing, finished inventory and production line work as OEMs shift capital-intensive steps upstream.
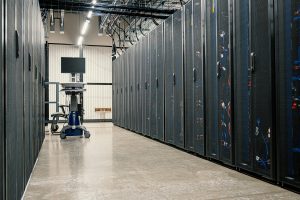
Kibar Americas expects data center cooling growth to add fin stock demand while US foil supply remains reliant on imports.
Aluminum content per vehicle is rising as automakers expand use of extrusions, sheet, and castings.
Recycler demand rebounded in August as obsolete scrap availability narrowed, inventory drawdowns persisted and forward oversupply expectations disappeared.
August survey results showed stronger demand alongside shorter measured lead times, while imports became more competitive and forward expectations moved toward balance.